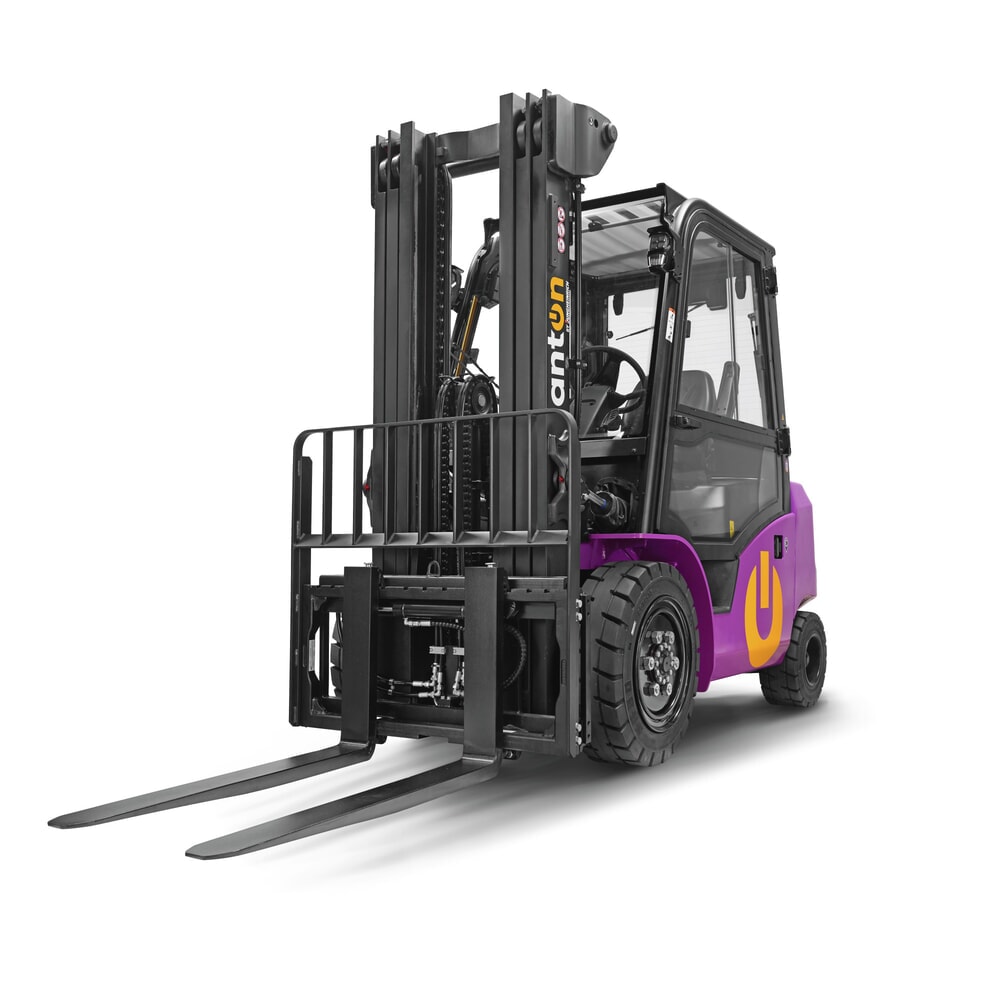
Model illustration
AntOn by Jungheinrich / Electric forklifts
AntOn CBH 2.0 V3
AntOn CBH 2.0 V3 | 2,000 kg | 4,800 mm lift | Full heated cab / Comfort
Tell us about your site and working day for a York quotation covering the selected truck, charging, delivery and support.
Part of Jungheinrich’s Mid-Tech range
Practical electric handling, competitive pricing and Jungheinrich quality assurance, supplied and supported by York. What is behind AntOn? →
Technical specification
| Capacity | 2,000 kg |
|---|---|
| Lift Height | 4,800 mm |
| Fuel Type | Lithium electric |
| Operation | Seated, four-wheel counterbalance |
| Load centre | 500 mm |
| Cab | Full heated cab / Comfort |
| Mast Type | Three-stage with free lift |
| Closed Mast Height | 2,265 mm |
| Side Shift | Attached |
| Battery voltage | 80 V |
| Fork length | 1,150 mm |
Nominal capacity depends on load centre, mast, attachments and working height. We’ll check your application before supply.
Buying equipment · Tax allowances
Your forklift purchase may qualify for a 100% tax deduction
Eligible businesses may be able to deduct the full qualifying cost from taxable profits through full expensing or the Annual Investment Allowance. The saving depends on your tax position and purchase arrangements. Ask your accountant to confirm eligibility before ordering.
Which allowance could apply?
Full expensing: companies subject to Corporation Tax can claim a 100% deduction for qualifying new, unused main-rate plant and machinery. Equipment bought to lease out is generally excluded.
Annual Investment Allowance (AIA): eligible businesses can claim a 100% deduction for qualifying purchases, including eligible second-hand equipment, within their available allowance. The usual limit is £1 million for a 12-month accounting period; adjustments and sharing rules can apply.
The equipment brand or power source does not, by itself, establish eligibility. Your accountant should check the asset, business use, accounting period and available relief.
What does a 100% deduction mean?
It reduces taxable profits by the qualifying cost. It is not a refund of the purchase price.
Illustration: a £20,000 qualifying purchase could reduce Corporation Tax by £5,000 where the full deduction reduces profits taxed at 25% and sufficient taxable profits are available. This is an example, not a guaranteed saving. VAT recovery is separate; later disposal can create a tax adjustment.
Buying outright, hire purchase or rental?
Qualifying hire purchase can be eligible for capital allowances. For AIA, HMRC states that when the item starts being used, the capital payments under the contract can qualify; interest is excluded from AIA.
Ordinary rental does not normally give the customer capital allowances on the equipment purchase. Ask your accountant to check the specific agreement, tax treatment and claim timing.
Official HMRC references
Use these government sources to check the rules with your accountant:
Guidance checked 7 October 2026 · General information, not individual tax advice · Tax rules and circumstances can change